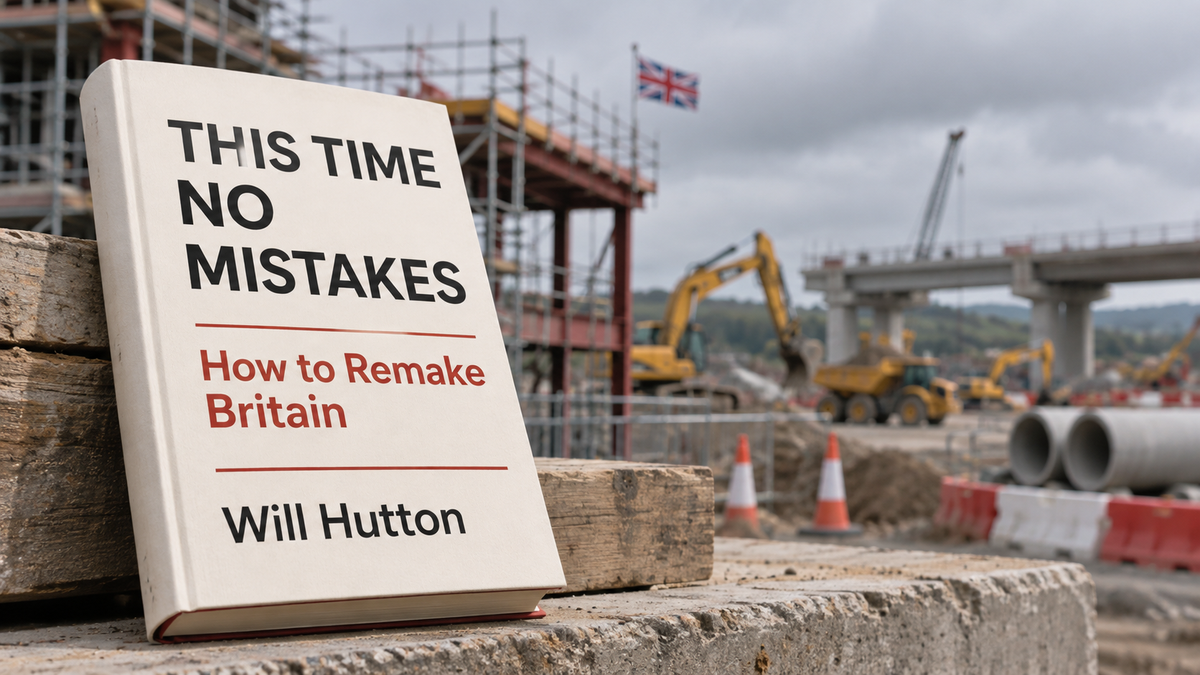
Will Hutton’s This Time No Mistakes is the sort of book that will put a lot of people off. In the words of one Amazon reviewer:
“Readers who are left wing will agree with and enjoy this tome. Otherwise, they will find it to be a rather long sermon. My copy is on its way to Oxfam.”
But Hutton is a serious and influential centre-left political economist, and there is an idea in the book that deserves a hearing even from readers who have no intention of signing up to his wider politics. Hutton summarises this idea in a way that I doubt would be offensive to either left-wing or right-wing sensibilities:
“Above all, we must learn to invest in ourselves and build the public and private institutions to do that.”
I'm interested in this sort of thinking because it potentially offers a solution to the conundrum that underpins this whole blog: how can we invest in resilient digital infrastructure in the UK? At the same time, it speaks to my commercial experience as an investment manager.
I know that the best investor for a long journey is a happy investor: someone who has chosen to be there, believes in the potential for meaningful capital gain, and has a credible prospect of receiving dividends along the way. For me, "learning to invest" starts from the bottom up, with investment pitches, shareholder agreements, investor dashboards and performance reports that help people understand what they're backing and how it's performing. Hutton, inspired by historical projects like Roosevelt’s New Deal, perhaps takes a more top-down and institutional approach to the challenge. Overall though, we end up in much the same place: a call to help a new generation of investors discover the “we” in investing, particularly where the “we” brings better returns or less risk without compromising the needs of “me”.
There is a striking backdrop to this need for a rethink. British pension funds now devote a much smaller share of their portfolios to UK company shares than they did a generation ago, with defined-benefit schemes increasingly favouring gilts and defined-contribution schemes investing heavily overseas. Meanwhile, foreign investors own a growing share of Britain’s listed companies. The connection between British savings and ownership of British businesses has weakened. Hutton argues that we have lost the notion that collective ambition, backed by the right institutions, could open up profitable opportunities that individual savers could not bring into existence alone.
This need not be an argument for telling people where to invest. The question is how the government could help create opportunities here that people understand, believe in and willingly choose over the alternatives—so that more of our savings help build things the country needs. The gilt market, in its current form, isn't designed to achieve this: although it connects private capital with government borrowing, it doesn't establish a direct relationship between investors and the projects their money helps to finance.
Here's how I think Hutton's alternative could work in practice: Imagine a UK fund that only invests in data centres that are officially accredited for meeting certain national responsibilities, including an ability to keep operating during an emergency when overseas services or connections may be disrupted. The government could support these data centres by being a dependable customer for public-sector workloads, giving investors a clearer basis for expecting dividends in ordinary times, rather than only a speculative payoff when there’s a crisis. The government could also help coordinate power connections, while local residents could be offered discounted shares so that the community hosting the physical development could share in its success. The Baywind project in Cumbria in the 1990s offers a basic template for this, albeit in renewable energy rather than digital infrastructure.
Even with that support, the investment would have to stand up commercially. But there is another, perhaps taller hurdle: why should savers trust a project promoted by politicians? This is, I think, a key weakness in Hutton's approach that would need to be tackled early on if it is to stand any chance of working.
A national ambition might make the proposal more appealing, but it would not make the people running it more competent or their incentives more aligned with investors. The UK has seen enough failures where public purpose met private money, the collapse of Carillion among them. Now, anything that sounds similar (even if it technically isn’t) faces an uphill battle.
It’s telling that on the same day that The Observer newspaper published one of Will Hutton’s articles expounding his ideas, The Sunday Times reported a story that pushed directly the other way. Welsh council pension funds, investing together through the Wales Pension Partnership, had put around £68 million into Bute Energy, a politically supported wind farm developer. Bute’s parent company went on to pay a £58 million dividend to its four shareholders, although Bute has yet to complete a single wind farm. Where the money for that dividend came from is disputed, and the investment may yet come good. But the focus of the news coverage was on the politicians involved: these were public-sector pension funds, not distant City institutions, and the investment was reportedly approved despite warnings about the risks.
A government-supported UK data centre fund would therefore have to work doubly hard to earn its credibility. Savers would need to know who makes the investment decisions, what those people are paid, what could go wrong, and how their money reaches the infrastructure being promised. They would also need the confidence to ask those questions and expect answers they can understand.
The current lack of a healthy connection between private investors and national projects need not be permanent. Rebuilding that connection could be seen as a deeper interpretation of Hutton’s call to “learn to invest in ourselves”. What we need to rediscover is the possibility of pursuing our own financial ambitions by helping to build something of shared value. Better investment institutions would be part of that, but so would helping people become more capable of judging the opportunities those institutions offer – a knack that is difficult to develop when so many of our investment decisions are delegated to institutions or buried inside diversified funds. I’m interested in whether a new national investment policy could do both: make worthwhile projects possible, and give more people the knowledge and confidence to decide whether to back them.